Mortgage valuation in Amsterdam for self-employed buyers: plan the evidence
Prepare a self-employed mortgage valuation in Amsterdam by coordinating the property report with income evidence, lender timing and NHG conditions.
TL;DR: Five checks for a self-employed application
Prepare the self-employed mortgage valuation by fixing the lender’s report requirements and the property question first. At the same time, ask who will assess entrepreneur income and which records that person needs. Keep the valuation date and the income-statement date visible. Collect the property documents, arrange the inspection, then match the finished report and current income evidence to the lender’s written request. Keep these numbers apart: more than 12 months in business, 5 working days for the NHG income statement after all documents arrive, 6 months of statement validity, the property’s market value, the 100% home-value ceiling and the 2026 NHG limit. Each belongs to a different part of the application.
- Ask the lender for the accepted report, validation, recipient and deadline.
- State the property purpose, address and valuation date in one sentence.
- Ask the adviser or income expert for the current entrepreneur-income records and timing.
- Collect property, VvE, leasehold, permit and renovation evidence and keep the income records separate.
- Inspect, review and hand over the report while the income evidence is still current. The NHG entrepreneur income statement has its own activity, document, timing and validity conditions.
Before requesting an Amsterdam valuation, a self-employed borrower can organise property records and lender questions with valuation preparation tools.
Are you self-employed and arranging a mortgage?
If you are self-employed, the mortgage process combines a property question with an income assessment. Keep the valuation date, property evidence and report requirements together, and give your lender or income adviser the business records used to assess affordability.
- buying an Amsterdam home through income from your own business;
- applying with a sole proprietorship, partnership or company income structure;
- arranging an income statement for an NHG-backed application;
- changing from employment to self-employment or combining employment and business income; or
- facing a lender deadline before the property inspection or report delivery. Have the address, purchase terms, lender or adviser, preferred valuation date and financing deadline available. Keep tax returns, accounts, bank statements and identity documents with the party that requests them. A general information form does not need those records.
Before you arrange the valuation
Write two timelines. The property timeline contains the lender’s accepted report, validation, inspection, valuation date, report recipient and delivery deadline. The income timeline contains the income-statement request, required records, preparation time, validity period and the person who answers questions about business income. The NHG process for an entrepreneur who has been independently active for more than 1 year states that the income statement is prepared within 5 working days after all required documents arrive and remains valid for 6 months. Those are process figures for that statement. They do not promise that a lender will decide the full application in the same time.
Why the property and income clocks differ
A market-value opinion describes a property for a stated date and purpose. It may address location, rights, condition, use and market evidence. It does not calculate business profit, decide which income a lender accepts or confirm that a tax return is complete.
If your Amsterdam decision also involves amsterdam mortgage valuation brief, keep its lender requirements separate from the property question here.
An income statement looks at the business and the records needed for the lender’s affordability assessment. The lender then combines income, debts, interest, costs, the proposed loan and the property report under its own conditions. The same person may answer several parts of the application, but the evidence still has different jobs.
The 100% home-value ceiling does not replace the lender’s assessment of income, interest and other obligations.
It sets a ceiling related to the home’s value.
It does not say that a self-employed buyer can borrow the full amount or that every cost belongs in the mortgage.
The 2026 NHG limit is €470,000, or €498,200 with the stated energy-saving provisions, subject to the associated conditions.
The amount is a published threshold.
The lender still assesses the property, income, report and application together.
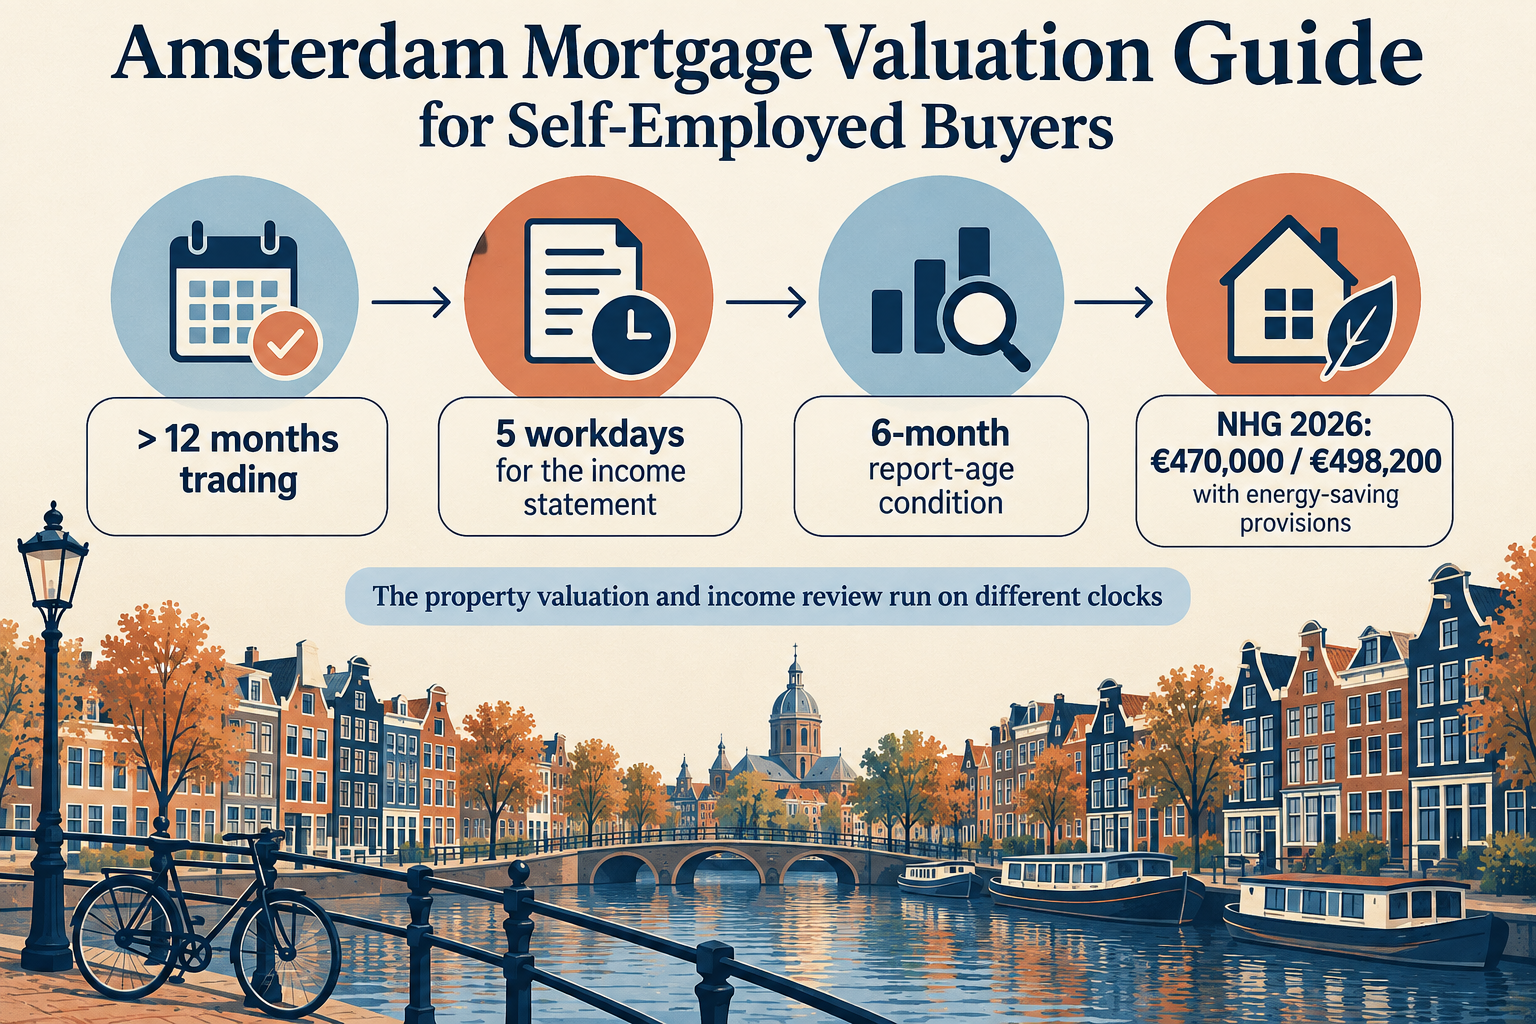
The infographic presents a timing strip, not a promise of approval. The activity period is an entry condition for the cited income-statement process, the 5-working-day figure starts after the required documents arrive, the 6-month figure describes statement validity and the two NHG amounts are published 2026 limits with separate conditions.
When you compare quotes, relate the valuation costs in Amsterdam to the scope, inspection, delivery conditions and follow-up you need.
A sound valuation report keeps the property, purpose, valuation date and recipient visible, so you can test whether the conclusion fits your decision.
Requirements and constraints
Place these fields in the property brief:
- Property: address, dwelling type, ownership, rights, usable area, condition and planned work.
- Purpose: purchase, refinancing, renovation finance or another named decision.
- Dates: valuation date, inspection date, report delivery date and lender deadline.
- Recipient: lender, validator, mortgage adviser or another named user.
- Property records: purchase agreement, deed, VvE records, leasehold terms, permits, plans, invoices and known defects.
- Business context: the income-statement status, person responsible for income assessment and a list of requested records, without including those records in a general question. The lender should be able to match the report fields for this valuation to the address, rights, date, assumptions and evidence. Ask the lender whether its application uses NHG, which report form it accepts and how old the report may be at submission. A report can answer the property question and still miss the application if the recipient, validation path or delivery condition is wrong.
Step by step: prepare the self-employed mortgage valuation
1. Ask the lender for the complete delivery rule
Request the accepted report type, validation path, recipient, report-age rule and delivery date. Keep the answer with the property address. If the lender uses a particular instruction, copy its wording into the brief so the valuer does not have to infer the purpose.
2. State one property question
Write: “Please value [address] for [mortgage purpose] as at [date], for [recipient].” Add apartment, leasehold, renovation or mixed-use facts. State whether the report concerns the current home or a planned condition after work.
3. Start the income timeline with the right owner
Ask the mortgage adviser, lender or income expert which entrepreneur-income assessment applies and which documents are current. The NHG process says an entrepreneur must have worked independently for more than 1 year for the Inkomensverklaring Ondernemer assessment, then sets a 5-working-day preparation period after all required documents arrive and a 6-month validity period. The professional handling the income records confirms how those rules apply.
4. Assemble the property records
Collect the purchase agreement, title or leasehold terms, VvE records, permits, plans, invoices and known defects. Label each record with its address and date. Business accounts can explain income; they do not replace a deed, a building record or the property evidence behind the valuation.
5. Schedule inspection and statement timing
Put the inspection, report delivery and income-statement dates on one calendar. A statement can be valid for 6 months and still be unsuitable if the lender has changed its document requirements. A report can arrive on time and still fail report delivery if the recipient or format is wrong.
6. Review the two records together
Compare the report address, purpose, valuation date, market-value figure, assumptions, limitations, recipient and validation with the lender’s instruction. Separately compare the income evidence, statement date and lender’s affordability request. Ask the relevant professional about any mismatch before submission.
Scenarios and variations
The business has passed the NHG activity threshold
More than 12 months of independent activity is a stated entry condition for the NHG entrepreneur-income statement process. It is not an income amount and it is not an approval. Keep the start date of the business and the statement request date in the income timeline so the expert can test the current facts.
All records arrive on one date
The NHG process describes preparation within 5 working days after all required documents arrive. “All” matters: a missing record can change the start of that period. Ask the income expert to confirm which documents are still missing and record the confirmation date.
A statement is six months old
The statement is described as valid for 6 months in the NHG process. The lender still decides whether it accepts the statement for the application, whether other facts are current and whether a new income assessment is needed. Pair the statement date with the lender deadline rather than relying on age alone.
The property is an apartment or leasehold home
Add the deed of division, VvE budget, minutes, reserve-fund information and major maintenance decisions for an apartment. Add the leasehold terms, canon information and relevant dates for leasehold. Keep business-income records in a separate folder.
The application uses NHG near a published limit
The 2026 NHG amount is €470,000, or €498,200 with the stated energy-saving provisions. A published limit is not a personal borrowing result. Keep the amount beside the lender’s current conditions and ask which purchase, market-value, work and loan figures belong in the calculation.
Common mistakes and stalled preparations
- Calling business turnover the income used by the lender: ask the income professional which figure and period it can use.
- Calling the property report an affordability decision: keep the market-value conclusion with the property records.
- Starting the five-working-day count before every required document has arrived: ask for a written completeness confirmation.
- Letting a six-month statement age without asking the lender: compare its date with the application deadline and current conditions.
- Using €470,000 or €498,200 as a loan promise: keep the NHG thresholds separate from affordability and cash requirements.
- Mixing company records with VvE or leasehold records: label each document by its question and address.
- Ordering a report without the lender’s recipient wording: obtain the accepted form, validation and delivery rule first.
- Sending tax or bank records through a general question form: ask about categories and keep personal records with the requested professional. When a preparation stalls, write the missing record, its owner and the date needed. The valuer can answer a property question. The lender or adviser can answer an application condition. The income expert can answer the entrepreneur-income question.
If you still have a question about the property, purpose or date, contact Taxateur Amsterdam with the question and without personal attachments.
After the report: review and repeat
Keep the lender instruction, property records, inspection details, completed report and income-statement date together. Before delivery, compare the address, purpose, valuation date, report user, market-value figure, assumptions, validation and delivery format. Compare the income statement and its validity separately. Repeat the comparison when the business form changes, a new income period becomes available, the lender changes, the purchase price changes, the valuation date moves, the property is altered or the report recipient changes. A new fact can affect one clock without affecting the other.
FAQ
Does being self-employed prevent a mortgage valuation?
No. The property can be valued in the usual way for a stated purpose and date. The lender separately assesses self-employed income, business records, debts, costs and product conditions.
How long must an entrepreneur be active for the NHG income statement?
The NHG entrepreneur-income statement process refers to an entrepreneur who has worked independently for more than 1 year. The income professional confirms whether the current business and records fit the process.
How long does the statement take?
NHG states that the statement is prepared within 5 working days after all required documents arrive. The date begins with a complete set of requested records, and the lender’s full decision has its own timing.
How long is the statement valid?
NHG states a validity period of 6 months. The lender can still ask for current information or apply its own acceptance rule.
Does 100% of home value mean I can borrow 100% of the purchase costs?
No. The 100% figure concerns the home-value part of the mortgage. Income, other obligations, lender rules and costs can change the amount and the cash needed.
Can the property valuation and income statement be ordered separately?
Yes, their purposes differ, but their dates and delivery should be coordinated. Ask the lender which documents and dates must be current when the report enters the application.
When to recheck the figures
NHG’s entrepreneur-income process, its 2026 limits and lender document rules can change. Recheck the more-than-12-month activity condition, 5-working-day timing, 6-month validity and €470,000 or €498,200 limit when a new application starts. Keep the source date beside any figure carried into your personal records. The useful delivery is simple to describe: the valuation answers the property’s market-value question, the income professional answers the entrepreneur-income question and the lender decides how the full application fits its current conditions.
A self-employed mortgage application has two clocks: the property report must answer a dated market-value question, and the income records must be complete for the lender's assessment. Put both deadlines in writing and ask a general question through the contact form if report delivery is unclear. Do not attach tax returns, bank statements or other sensitive records.
Ask a question about a self-employed mortgage valuation