Mortgage valuation in Amsterdam: check the three dates and limits
A mortgage valuation in Amsterdam should match the lender, valuation date and accepted report format. Read the 90 percent, 6-month and 3-in-12 checks in context.
TL;DR: Five checks before the lender sees the report
A mortgage valuation supplies the market-value opinion for a financing application. Start with the lender’s purpose and accepted format, then set one valuation date, collect property and mortgage information, commission an independent report and compare the result with the recipient’s conditions.
- Ask the lender for the accepted form, validation and submission deadline.
- Fix the purpose, valuation date, property and intended report user.
- Gather leasehold, VvE, renovation, permits and mortgage documents.
- Commission the report within the confirmed conditions.
- Review the value, assumptions, report age and open questions before submission.
If your Amsterdam decision also involves mortgage valuation for home movers in Amsterdam, keep its lender requirements separate from the property question here.
If you are also deciding on purchase valuation in Amsterdam, keep that purchase purpose separate from the mortgage or valuation question here.
Before you set the brief, define the market value in property valuation so the purpose and valuation date share one meaning.
If your Amsterdam decision also involves mortgage valuation checks for first-time buyers, keep its lender requirements separate from the property question here.
Does your lender need an Amsterdam mortgage valuation?
If a lender has asked for an Amsterdam mortgage valuation, pin down the report’s purpose, accepted form, valuation date and recipient before you arrange the inspection. That gives the valuer a precise property question while the lender handles income, borrowing capacity and monthly payments.
If your Amsterdam decision also involves mortgage valuation for Amsterdam investors, keep its lender requirements separate from the property question here.
Before you start
Ask the lender four questions in writing: which valuation format is accepted, whether validation is required, how old the report may be and who will receive it. Add whether the application uses NHG, whether the property is leasehold or an apartment, and whether renovation work changes the application. These details prevent a report that answers the wrong lending question. Use this short lender-question template: “For [address], purpose [purpose], valuation date [date], do you accept [format]? Is validation required? What report age and recipient rules apply? Are there earlier valuation services or renovation documents to disclose?”
What a mortgage valuation does
A formal valuation gives an opinion of market value for a stated purpose and date.
In a mortgage application, the lender uses that report alongside income, debt, loan-to-value and product checks.
The report answers the property-value question.
It does not decide whether your income supports the loan or whether a particular monthly payment suits you.
Three figures often appear in preparation conversations.
They belong to different rules.
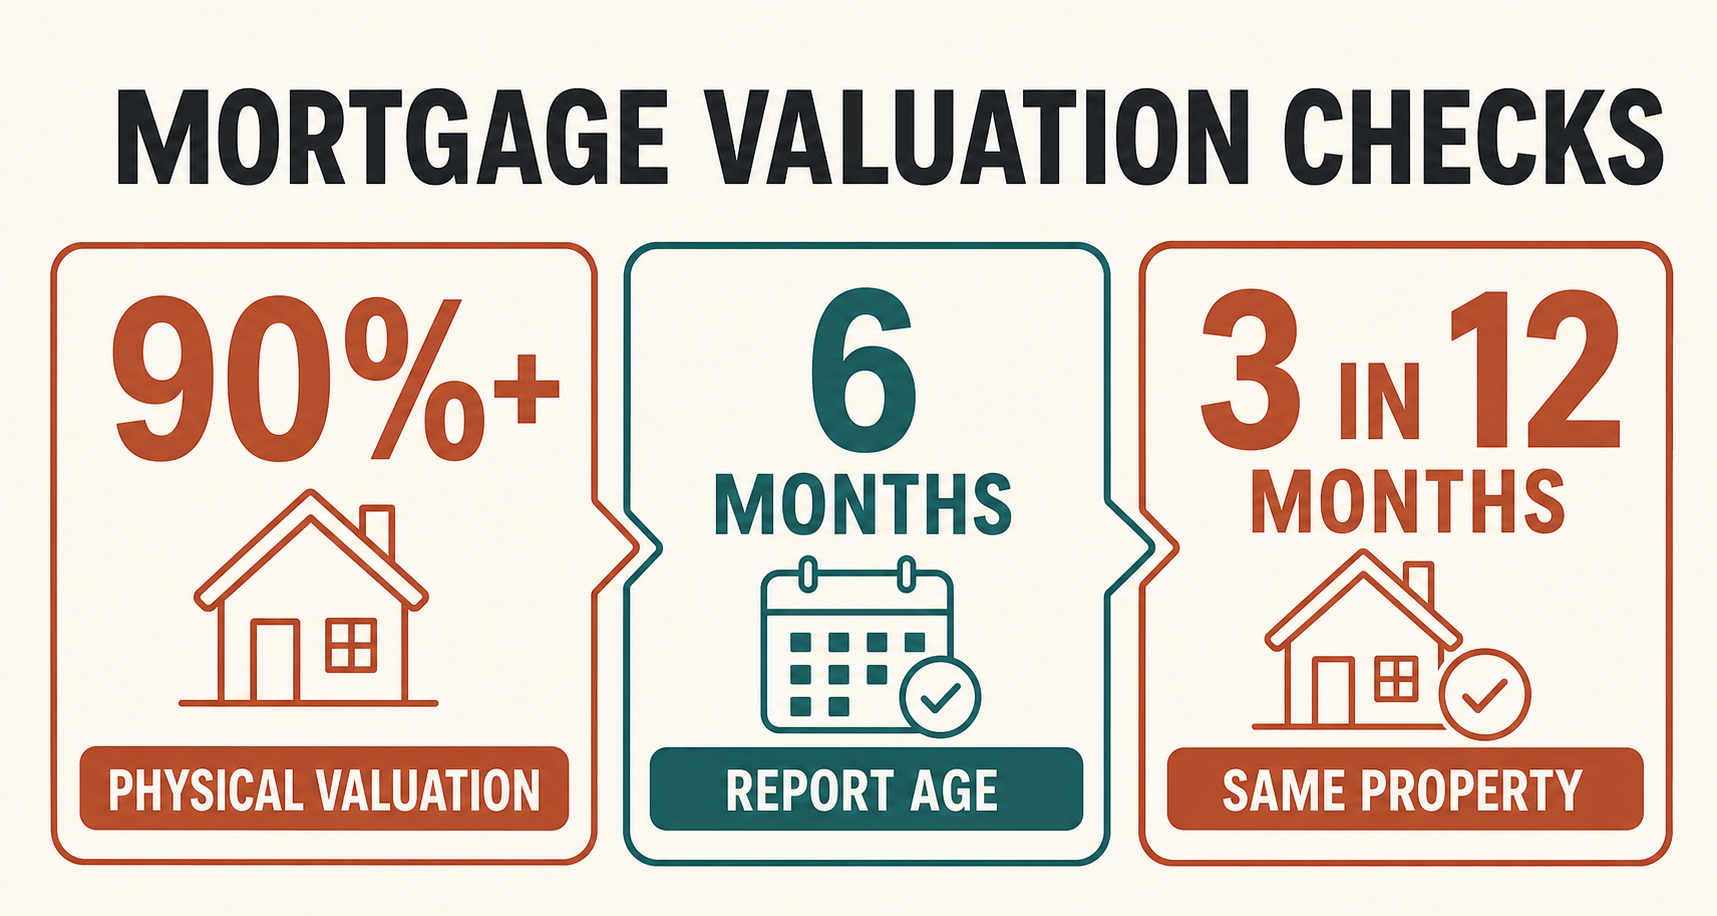
The NHG physical-valuation trigger and report-age rules apply in listed situations when borrowing exceeds 90% of market value and include a 6-month report-age condition from the valuation date in the relevant context.
The NRVT limit for residential valuation services describes a maximum of 3 professional valuation services for the same property in a contiguous 12-month period for financing by a licensed bank, with the addition dated 9 July 2026.
Three figures, three different rules
90%: In the listed NHG situation, borrowing more than 90% of market value can require a physical valuation. The ratio is intended borrowing ÷ market value × 100. It is not a personal affordability test.
6 months: In the cited NHG physical-valuation context, the report may be no more than 6 months old from the valuation date. Ask the lender which date it uses and whether a report commissioned for another purpose can be reused.
3 in 12 months: The NRVT figure concerns professional valuation services for financing by a licensed bank for the same property in a contiguous 12-month period. It is not a limit on questions, document exchanges or mortgage appointments.
The three figures help you ask precise questions. They do not combine into a universal mortgage formula. A lender outside NHG may use another threshold, format or age condition.
A sound valuation report keeps the property, purpose, valuation date and recipient visible, so you can test whether the conclusion fits your decision.
When you compare quotes, relate the valuation costs in Amsterdam to the scope, inspection, delivery conditions and follow-up you need.
Requirements and constraints
Prepare these five fields before you contact a valuer:
- Purpose: purchase, refinancing, increase, renovation or another finance event.
- Recipient: lender, validator, adviser and any other named reader.
- Format: physical, hybrid or another accepted report type.
- Date: valuation date, inspection date, report date and submission deadline.
- Property facts: address, type, usable area, leasehold, VvE, renovation and known defects.
The NHG requirements for a physical valuation describe independence and accepted validation in that NHG context.
The NRVT objectivity and independence rules say the valuer forms an own judgment and considers actual or apparent interests.
Share the facts and the finance purpose.
Do not ask for a predetermined figure.
Step-by-step: prepare the report
1. Get the lender instruction
Save the lender’s wording, product name, NHG status, required format, validation path and submission date. If the instruction is verbal, send a short email summarising it and ask for confirmation.
2. Fix the valuation question
Write one sentence such as: “Please value this apartment for the proposed purchase and mortgage application as at [date], for review by [recipient].” If the report must also show a value after renovation, say so before the inspection.
3. Assemble the property records
Collect the purchase agreement, floor plans, leasehold papers, deed of division, VvE budget and minutes, service-charge information, permits, invoices for work and any building report. Add mortgage balance or requested loan details only when the recipient needs them. Remove personal data that does not belong in the valuation purpose.
4. Commission and schedule
Compare the scope, report format, validation path, inspection timing and delivery date. Confirm who performs the valuation and whether the valuation purpose fits the recipient’s independence requirements. Keep the confirmation with the application.
5. Review before submission
Read the report purpose, date, property description, market value, comparable evidence, assumptions, limitations and recipient details. Ask about a mismatch before the lender receives the document. Keep a record of the question and the answer.
Scenarios and variations
An illustrative 90% calculation
If an illustrative requested loan is €450,000 and an illustrative market value is €500,000, the ratio is €450,000 ÷ €500,000 × 100 = 90%. This arithmetic only explains the number. It does not predict a lender decision, income test or accepted loan amount. The lender confirms whether its rule is triggered at, above or below that ratio.
A report older than 6 months
Check the valuation date, report date, lender product and purpose together. A report can be recent and still fail a recipient’s format or purpose requirement. Ask whether a new inspection, update or full report is needed.
A second valuation request
Tell the valuer and lender about earlier professional valuation services for the property. The NRVT 3-in-12 rule has a defined financing scope. The lender can explain how it applies to the current valuation brief.
Apartment, leasehold or renovation
Flag VvE decisions, reserve funds, leasehold conditions, foundation information and planned work early. A new floor plan or permit can change the property description. A renovation budget remains a cost estimate until the work is defined and completed.
If you still have a question about the property, purpose or date, contact Taxateur Amsterdam with the question and without personal attachments.
Common mistakes and stalled preparations
- Ordering a report before checking the lender’s format: ask for the acceptance condition first.
- Treating 90% as an affordability result: send the ratio question to the lender or mortgage adviser.
- Counting report age from the booking date: compare the report and valuation dates required by the recipient.
- Omitting leasehold or VvE documents: list the missing item and ask whether an assumption can be used.
- Asking for a preferred value: describe the purpose and evidence instead.
- Sending a report to an unintended recipient: confirm the recipient before release. If the preparation stalls, make a three-column note: open fact, person who can answer it, and date by which the answer is needed. A clear unresolved question is easier to resolve than a silent assumption.
After the report: review and repeat
Keep the final report, lender instruction and document list together. If the lender changes the product, the property changes, the valuation date moves or the report will go to another recipient, reopen the five-field check. Do not assume that an earlier report remains suitable after a material change.
FAQ
Is a mortgage valuation the same as a mortgage offer?
No. The valuation addresses market value for a stated valuation brief. The lender separately reviews income, debts, product rules and other conditions.
Does borrowing 90% always require a physical valuation?
The cited NHG wording refers to borrowing more than 90% in listed situations. Ask the lender about the exact product and threshold in your application.
Can I reuse a report from another lender?
Only if the new recipient accepts its purpose, format, valuation date, age and validation. Get that confirmation before relying on it.
Does the 3-in-12 figure limit my mortgage applications?
The NRVT wording concerns professional valuation services for financing by a licensed bank for the same property. It is not a general limit on applications or conversations.
What if my property is leasehold?
Supply the lease terms, ground-rent information and relevant dates. Ask the valuer which leasehold facts must appear in the report.
What should I do when the report contains an assumption?
Ask what evidence would resolve it, who can provide that evidence and whether the lender accepts the stated assumption. Record the response before submission.
Check the required report form, validation, report age and repeat-use rules with the lender before ordering. A market figure alone does not confirm that the document fits your finance records.
Ask a question about mortgage valuation checks